Equipment Finance. Structured Around Your Business.
Equipment Finance. Structured Around Your Business. We structure the right financing solutions to accelerate the transition to a more sustainable future.
Equipment supplied by our network of manufacturing partners
UPLease International BV
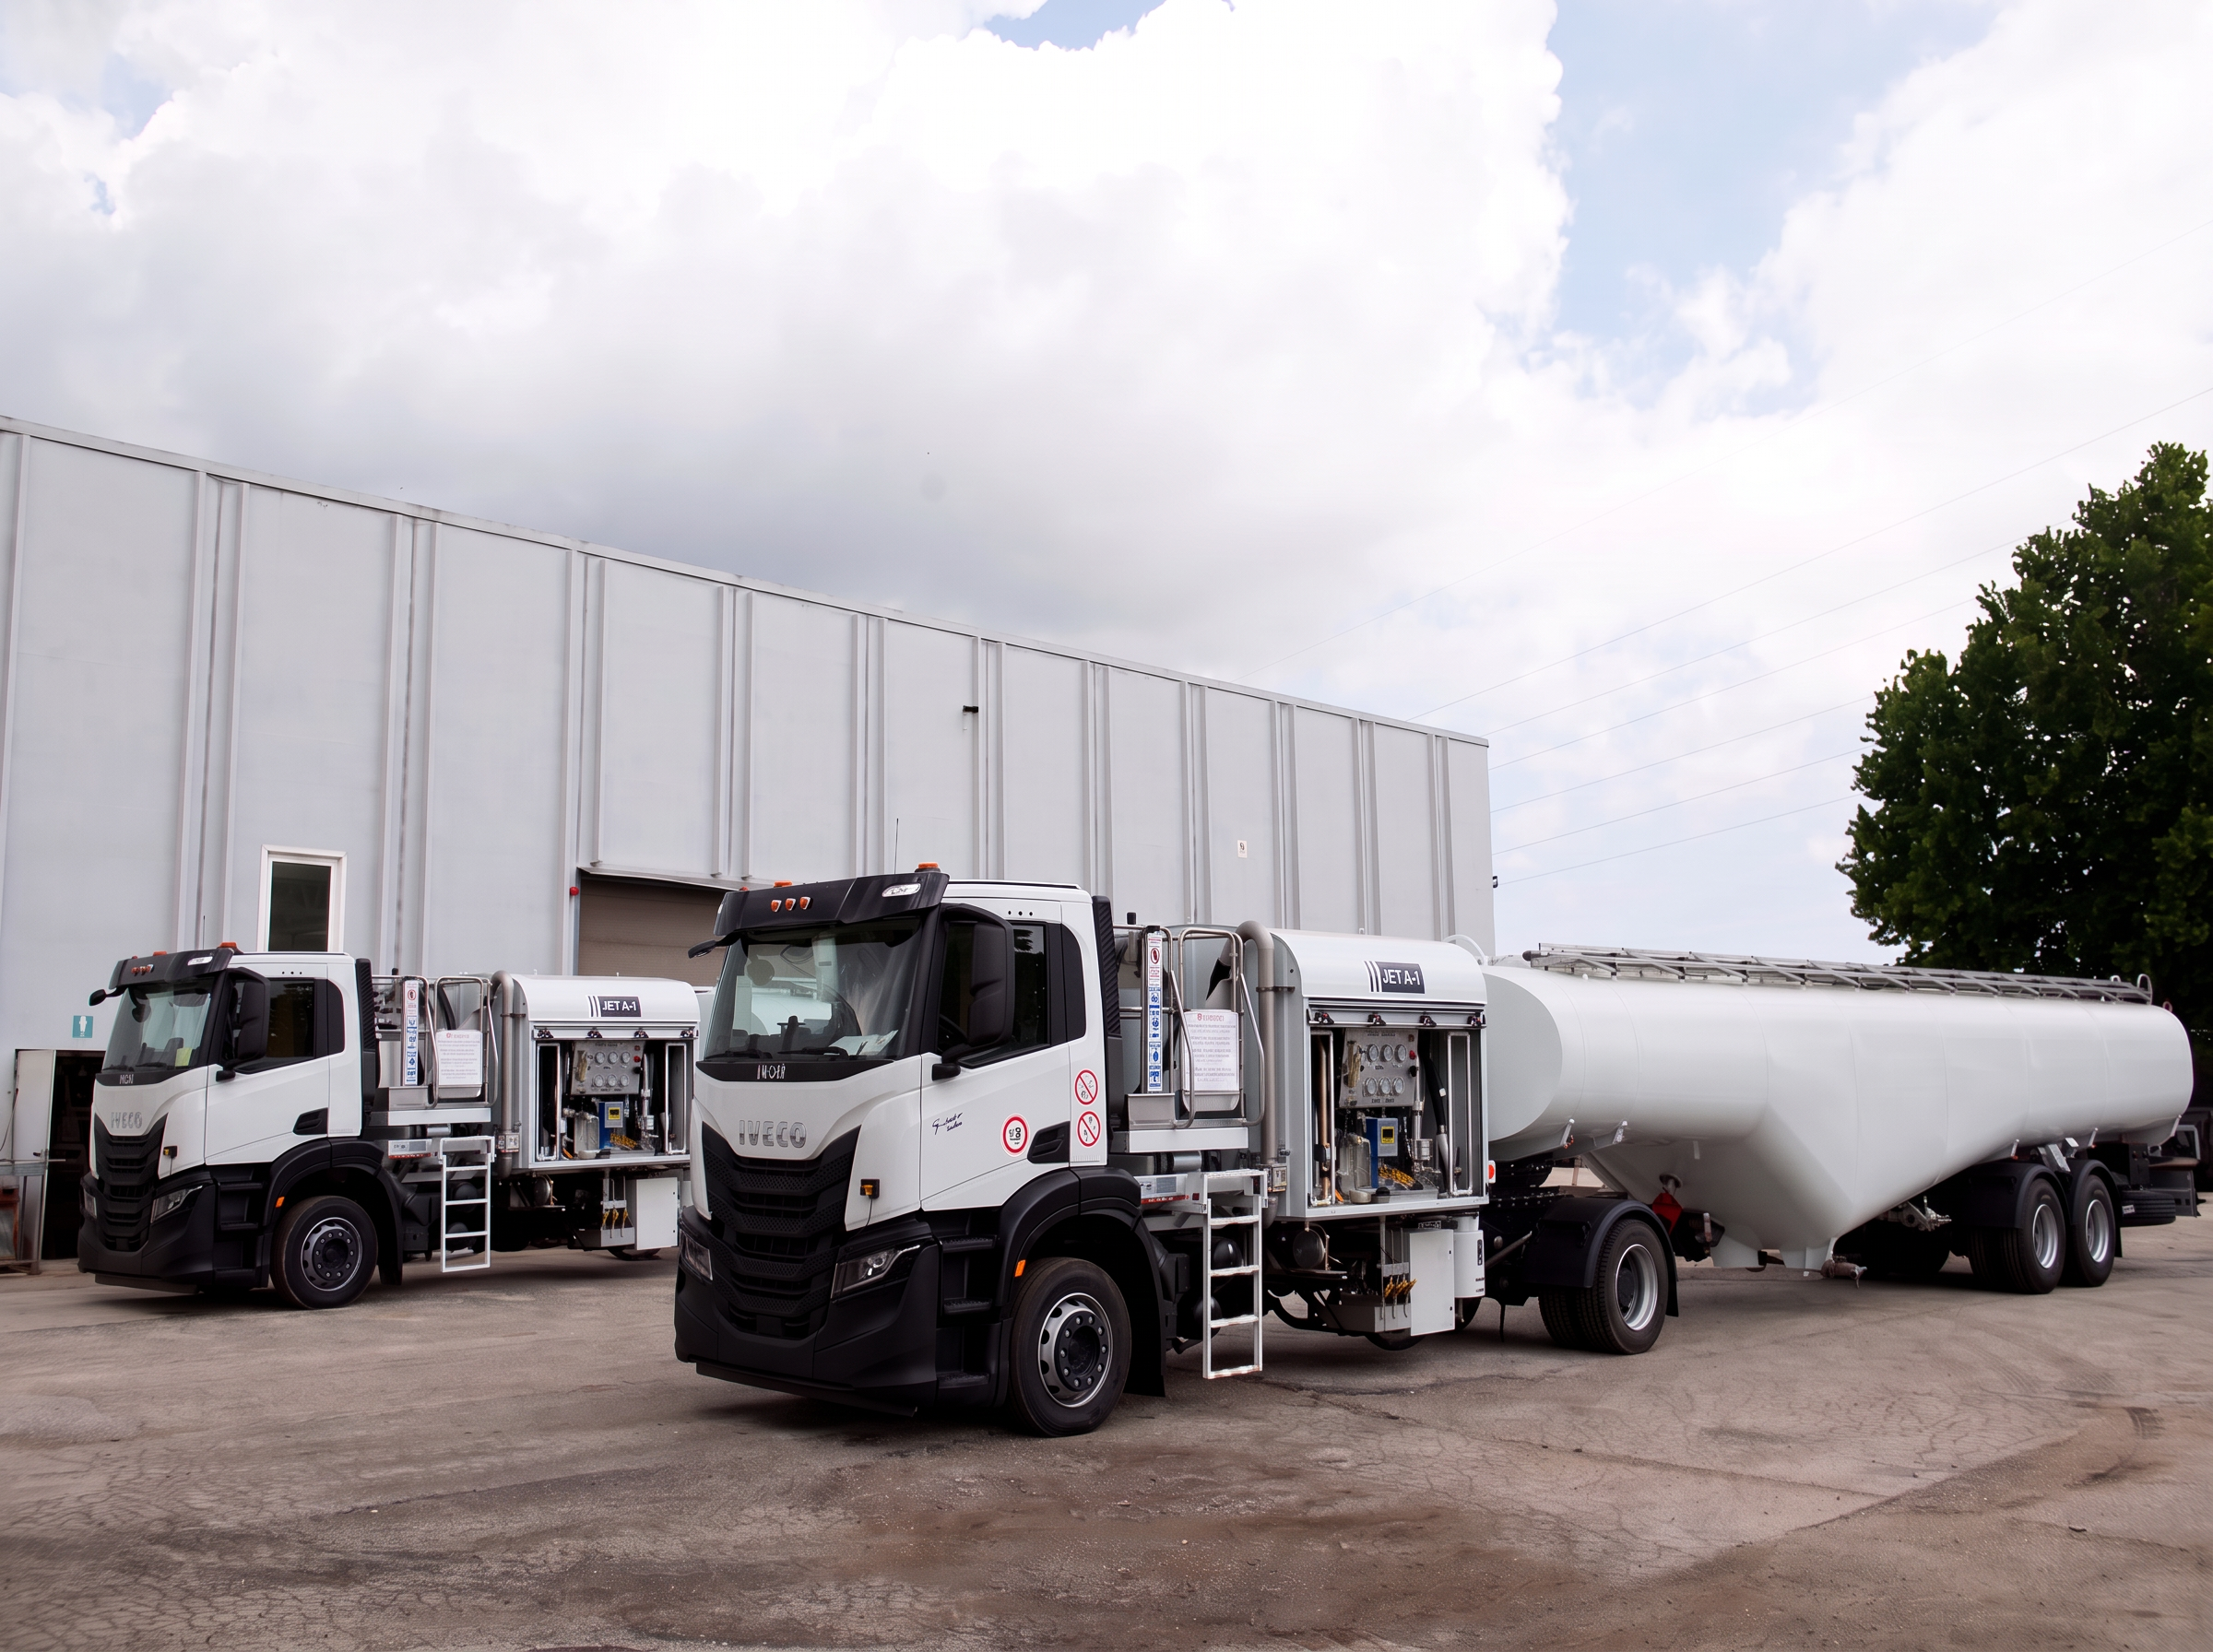
UPLease International BV, based in Brussels (Zaventem), is the captive finance company of JM Enterprise, a leading Italian manufacturer of aviation refuelling equipment with more than 40 years of experience. Beyond refuelling, we finance the full range of aviation ground equipment: GSE, electric equipment and airport infrastructure.
Finance the use, not the ownership
Your GSE assets go operational without tying up cash or your existing bank lines.
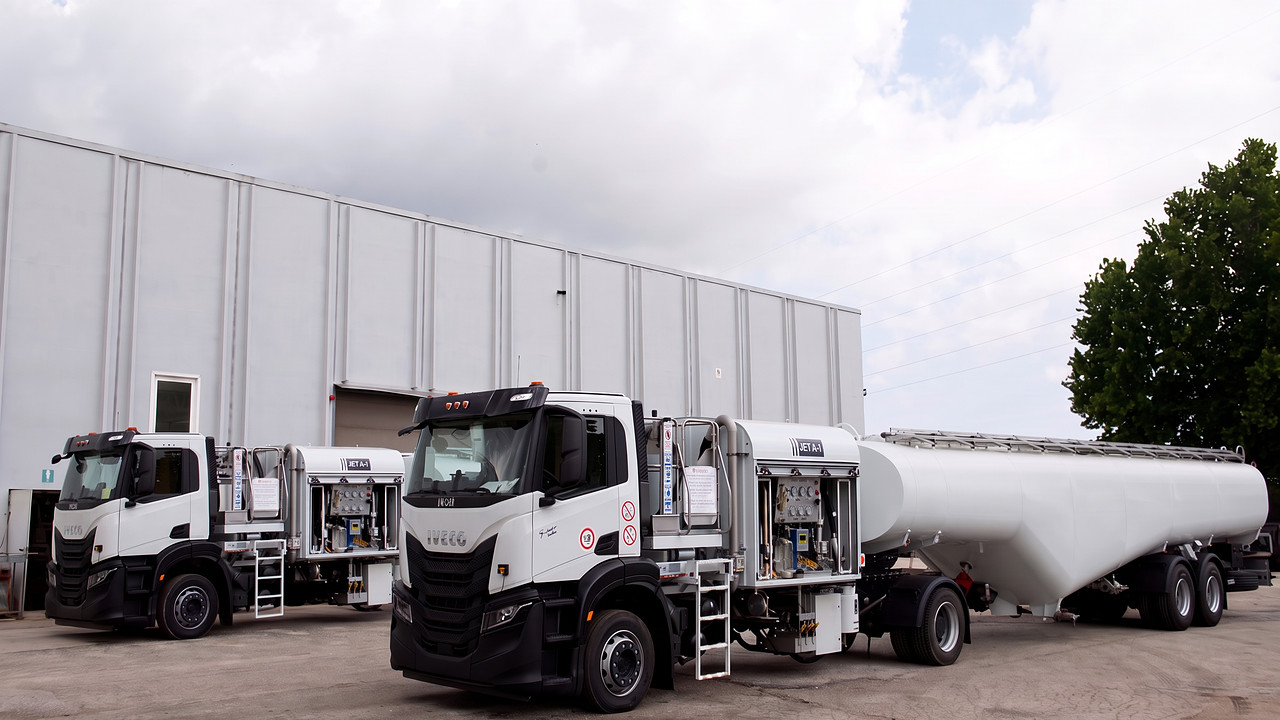
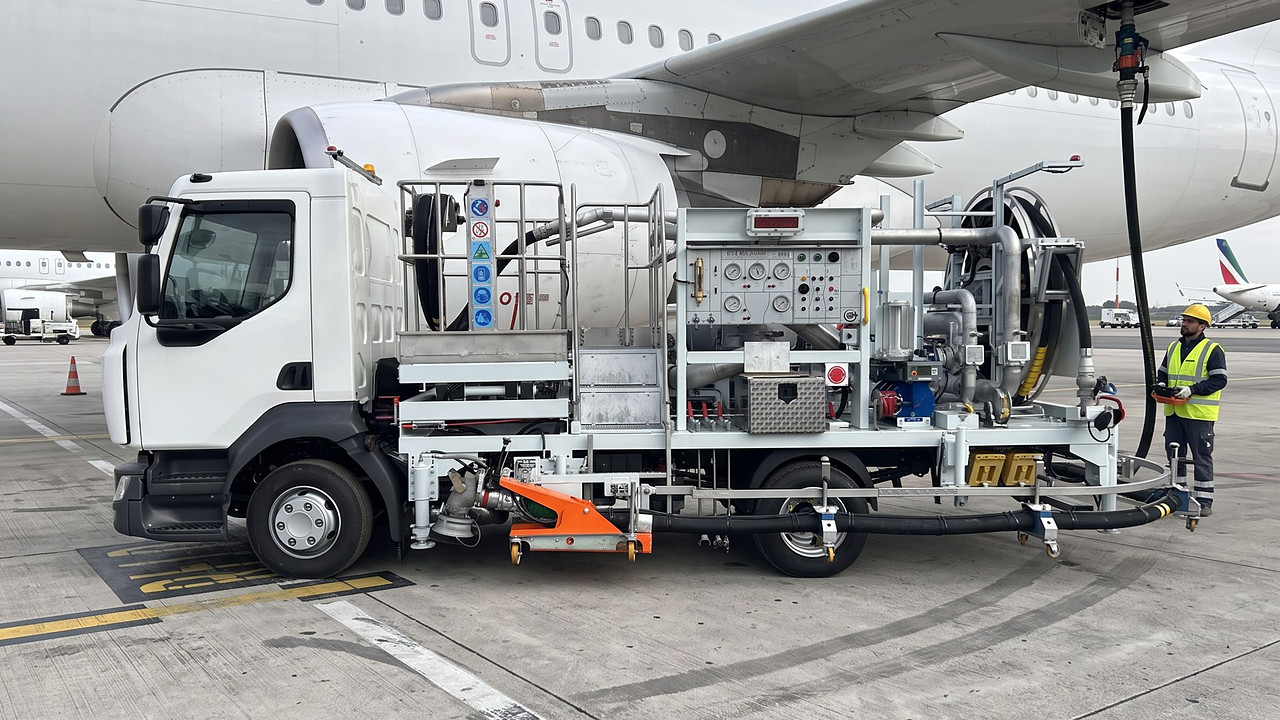
Refuellers
Sustainable
Environmental commitment
4
Leasing solutions
100%
GSE focus
IFRS 16
Integrated treatment
In motion
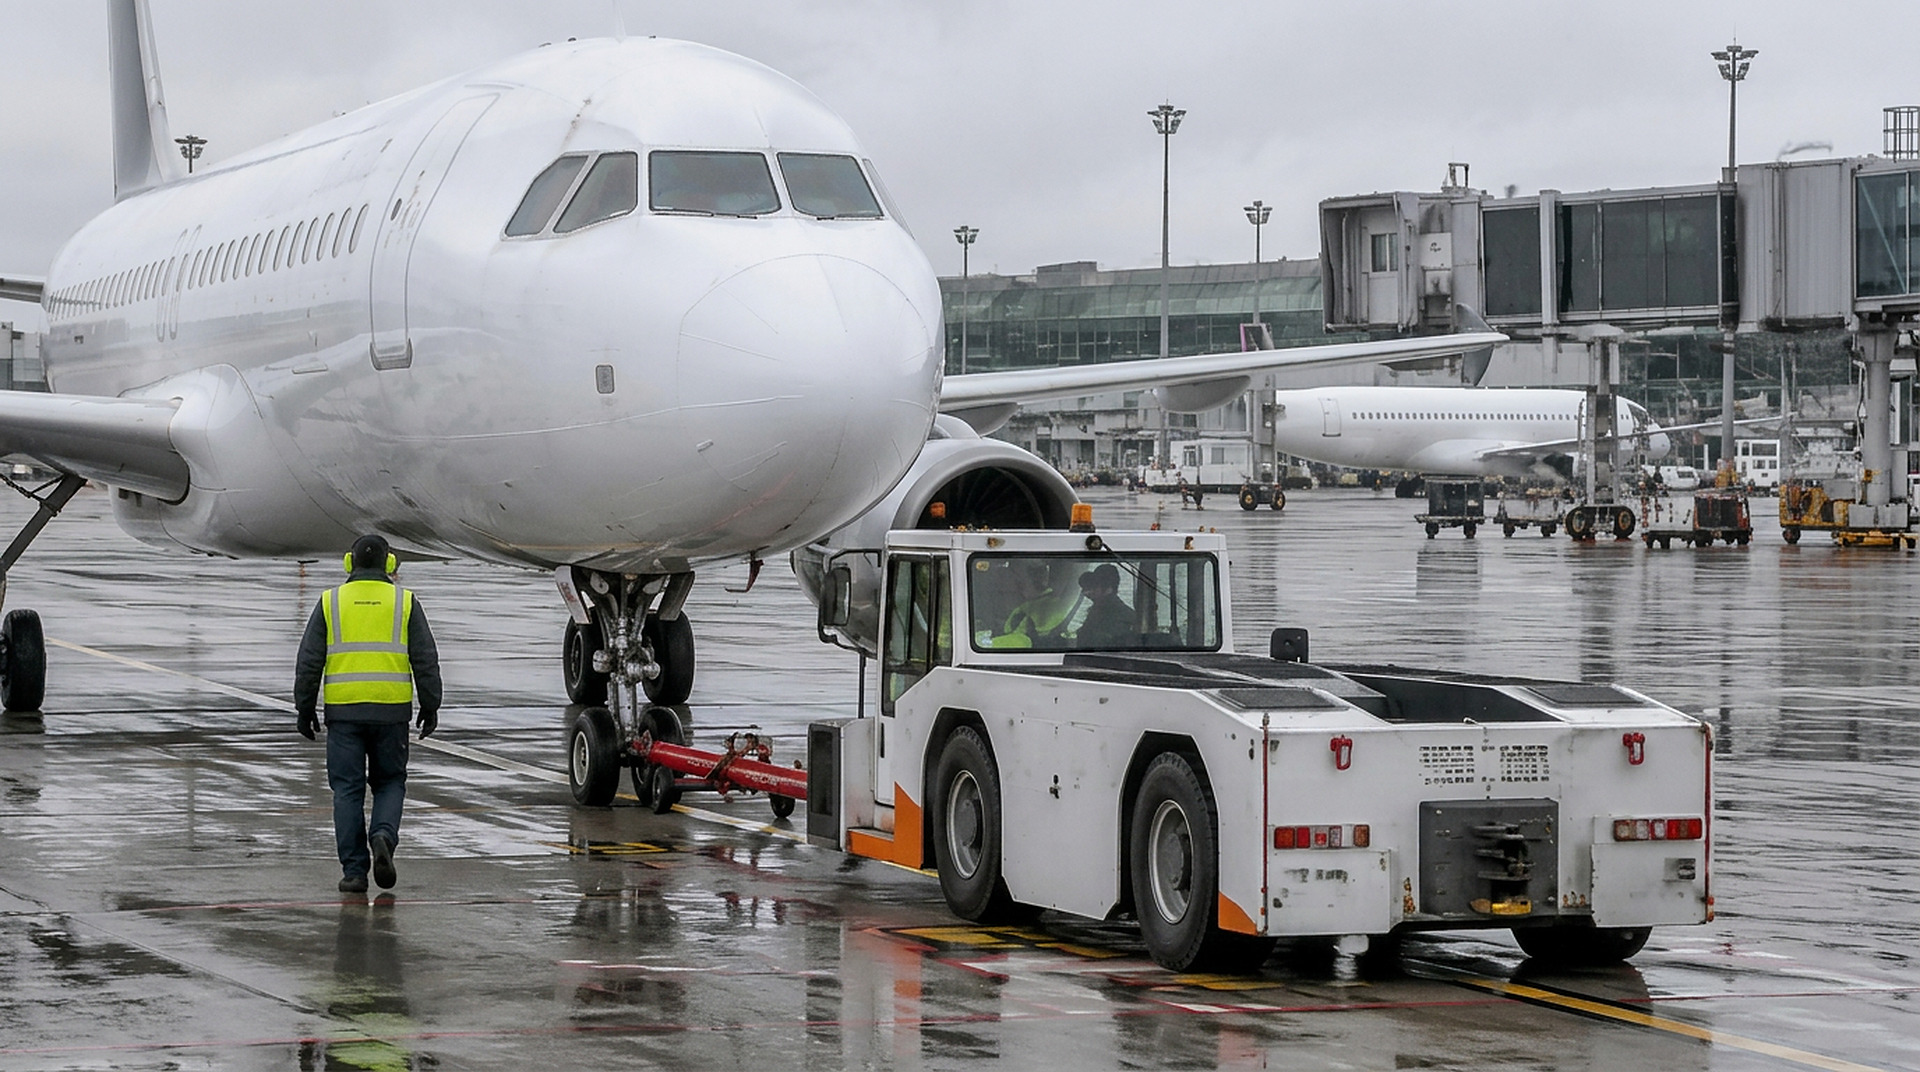
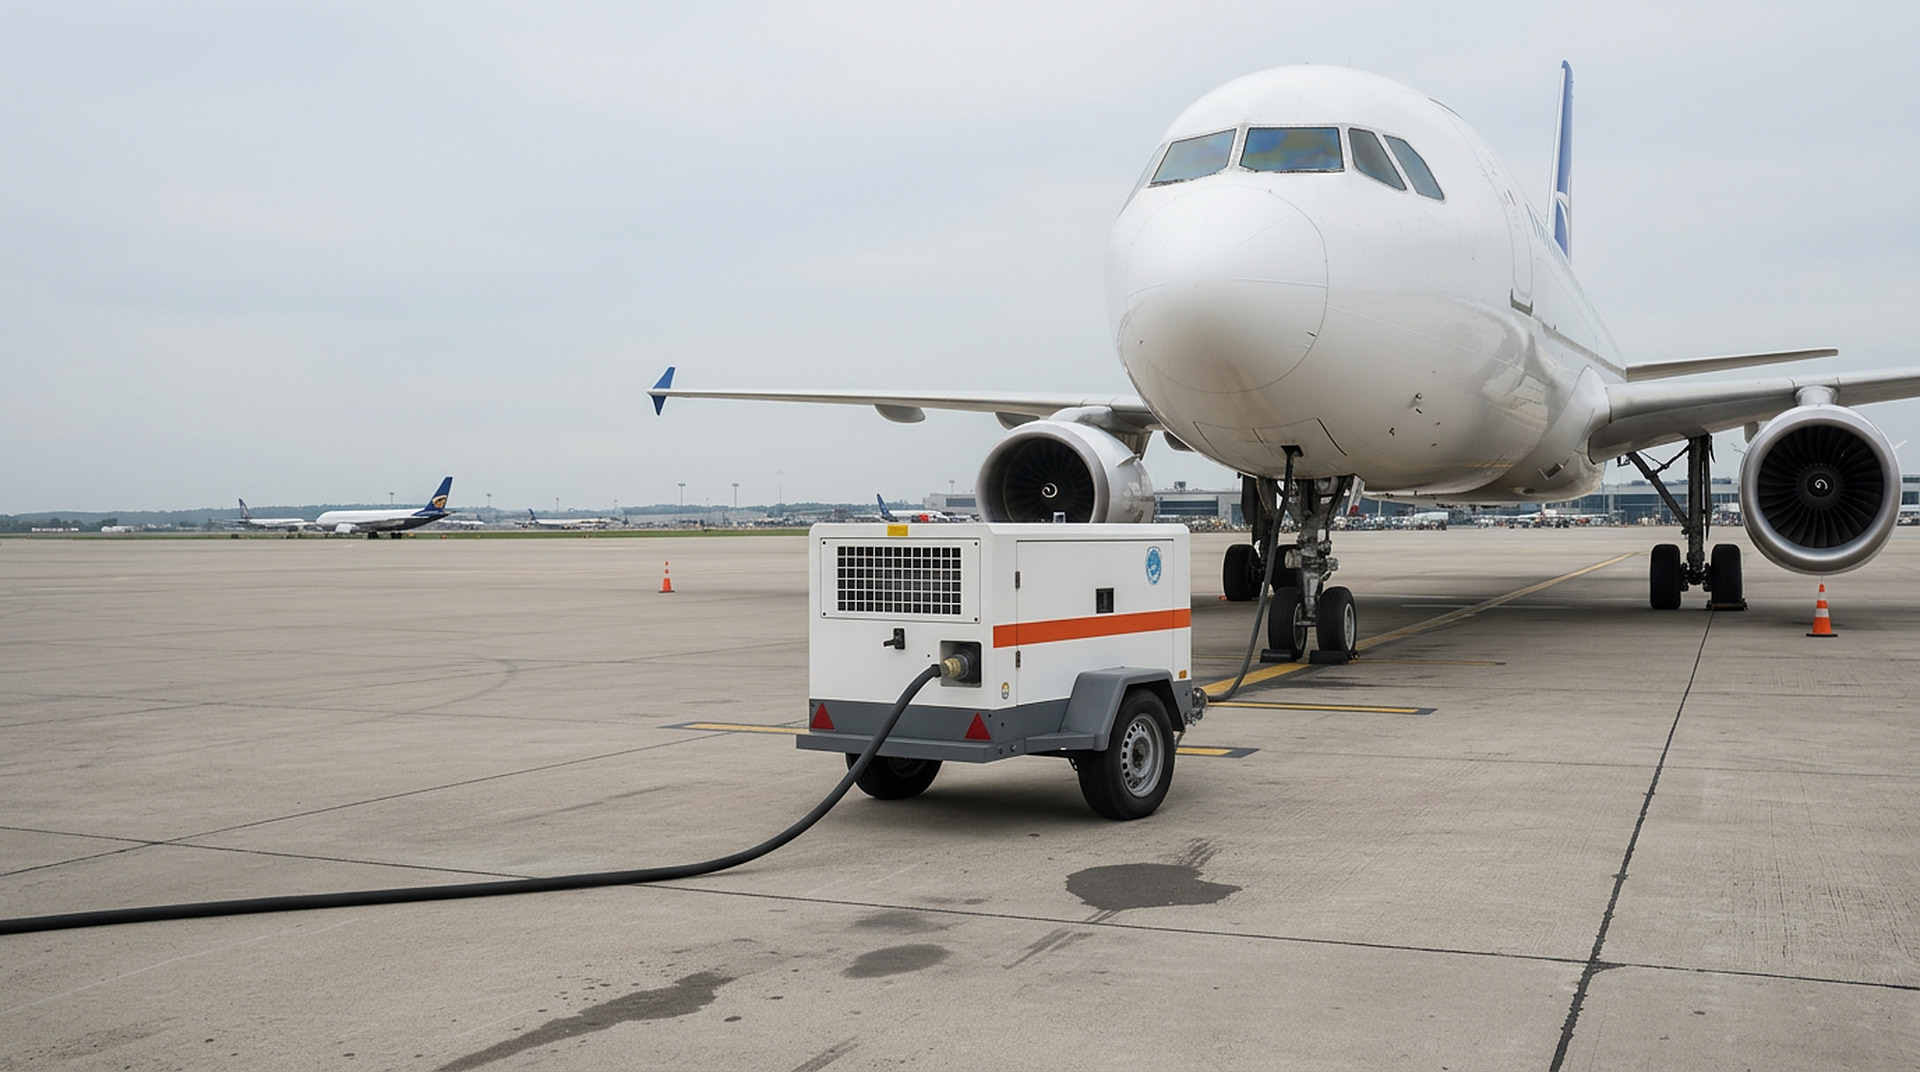
Ground Support Equipment, in action.
Aircraft refuellers, hydrant dispensers, GPUs, pushback tractors, belt loaders | UPLease finances the full GSE ecosystem that keeps airports running, anywhere in the world.
Our solutions
4 Solutions. One logic: align financing with the actual usage of your GSE fleet.
Compare in detailStandard Lease
Use it. Return it. Stay agile.
- Term
- 24 to 84 months
- Exit
- Return, renewal or acquisition at prevailing market conditions
- Optimised rentals, RV absorbed by UPLease
- Zero obsolescence risk
- Operational flexibility at end of contract
Pay-Per-Use
Pay for what you use. Nothing more.
- Term
- Modular, based on usage metric
- Exit
- Return or renewal
- Cost aligned with actual activity
- Optimised balance sheet, variable portion off-debt
- Zero under-utilisation risk
Short-Term Lease
Fast. Flexible. Ready to deploy.
- Term
- 4 weeks to 12 months
- Exit
- Simple return
- Off-balance sheet possible (IFRS 16 / ASC 842 short-term exemption)
- 100% OpEx, simple accounting
- Fast setup
Sale & Leaseback
Free the cash tied up in the fleet you already own.
- Term
- Depends on the chosen leaseback structure
- Exit
- UPLease becomes the owner; you remain the operator
- Immediate liquidity at closing
- Zero operational interruption
- Any brand taken over
Pay-Per-Use
Equipment-as-a-Service applied to GSE.
UPLease's Pay-Per-Use model bills your GSE equipment based on actual usage: rotations performed, operating hours, utilisation cycles. It is the only model that truly aligns the cost of the equipment with its operational use.
Cost aligned with actual usage
You pay per asset operating hour or per rotation. The invoice tracks the equipment's effective use.
Financing aligned with usage and seasonality
The variable component absorbs activity troughs, no more idle amortisation on a GSE unit that isn't running.
Residual risk carried by UPLease
Residual value risk absorbed by UPLease. Maintenance options available to suit your needs. You stay focused on your core ground operations.
IFRS 16 optimisation
The usage-indexed variable component is excluded from the lease liability, reducing on-balance-sheet debt.
IFRS standards
IFRS 16: understand the balance-sheet impact of each structure.
Since 2019, the IFRS 16 standard requires balance-sheet recognition of nearly all lease contracts: right-of-use asset and lease liability. UPLease structures every contract with this accounting constraint built in from day one.
- Right-of-use and lease liability calculations delivered with each offer.
- Short-term exemption (≤ 12 months) applied where available.
- Pay-Per-Use variable component excluded from the lease liability.
| Structure | On balance sheet (IFRS 16) | Optimisation |
|---|---|---|
| Standard Lease | Right-of-use + lease liability | Smoothed cost, residual risk transferred |
| Short-Term Lease | Off balance sheet possible if ≤ 12 months | Short-term exemption, at the lessee's election |
| Pay-Per-Use | Minimum fixed portion only | Variable excluded from lease liability |
| Sale & Leaseback | Adjusted right-of-use + lease liability | Monetise the asset, retain use |
Indicative presentation for groups reporting under IFRS 16. Under US GAAP (ASC 842), lessees also recognise leases on balance sheet, whether classified as operating or finance; the classification mainly affects how the cost is presented in the income statement. In French GAAP individual accounts (PCG), lease payments are generally expensed and finance lease commitments are disclosed in the notes. The short-term exemption (12 months or less) and the exclusion of usage-based variable payments from the lease liability exist under both IFRS 16 and ASC 842, subject to conditions. The final accounting treatment of a contract depends on the analysis performed by the lessee and its auditors under the applicable framework. This table is neither an accounting opinion nor a contractual commitment from UPLease on the treatment retained.
Product families
The full GSE range, financed under a single master agreement.
Process
From request to GSE on the apron: four seamless steps.
- ●
01
Equipment brief
You describe your GSE requirements, your base of operations and your renewal cycle.
- ●
02
Financial study
Case analysis, offer structuring and the related IFRS treatment.
- ●
03
Signature
Electronic contract, clear conditions, direct integration with the GSE supplier.
- ●
04
Commissioning
Manufacturer payment, on-site delivery, start-up.